US Tax Returns, Filed Correctly — From Form 1040 to 1120, 5471 and 5472
One licensed US CPA firm for your personal return, your company’s return, and the international forms most preparers miss. Whether you file a 1040, a 1040-NR, a 1065, an 1120-S or an 1120 — we determine what you owe, what you must report, and what you can stop worrying about.
Trusted by individuals, founders and growing companies
From single-owner LLCs and W-2 households to funded startups and foreign-owned US entities — clients rely on Manay CPA to get every required form filed on time.


From First Call to Filed Return — Four Steps
You don’t need to know which forms apply. That’s our job. Here’s how a return gets done.
Book a Free Call
Tell us who is filing: an individual, a household, an LLC, a corporation — or all of the above. No documents needed at this stage.
We Scope Your Filing
We confirm your residency status, entity type and ownership structure, then list every federal, state and international form you’re required to file — with a flat-fee quote.
You Upload Your Documents
W-2s, 1099s, K-1s, financial statements, foreign account balances — shared through our encrypted client portal against a checklist built for your exact return.
We File & Plan Ahead
We e-file your federal and state returns, walk you through the result, and flag next year’s estimated payments, elections and reporting obligations before they become problems.
Personal, Business and International — One Team, One Answer
A US-based, licensed CPA firm where cross-border returns are a core practice, not an exception.
Your Return and Your Company’s Return, Reconciled
K-1s, basis, distributions and reasonable compensation are decided at the entity level and paid for on your personal return. We prepare both sides, so the numbers agree before filing rather than after.
International Forms Are Our Daily Work
Form 5471, Form 5472, 1040-NR, dual-status years, treaty positions, GILTI, FBAR and Form 8938. These are the filings that carry five-figure penalties — and the ones generalist preparers most often skip.
A Named CPA, Available Year-Round
You get a dedicated CPA in our Atlanta office — not a seasonal preparer or an overseas call center. We answer in June and November too, when the decisions that shape your April return are actually made.
Every Return Type — Federal, State and International
Individual, business, nonresident and information returns, prepared and e-filed by licensed US CPAs.
Form 1040 — Individual Returns
W-2 income, self-employment and Schedule C, rentals, capital gains, crypto, RSUs and stock compensation, itemized deductions and credits. Includes Schedule C filers and sole proprietors.
Form 1040-NR — Nonresident Returns
Nonresidents with US-source income: investors, visa holders, US rental property owners and founders. Substantial Presence testing, dual-status years and treaty-based positions on Form 8833.
Form 1065 & Form 1120-S
Partnerships, multi-member LLCs and S-corporations. Partner and shareholder K-1s, basis tracking, reasonable compensation reviews, and late S-election relief where it applies.
Form 1120 — C-Corporations
US corporations of every size, including startups with investors and US subsidiaries of foreign groups. Book-to-tax reconciliation, NOLs, R&D credits and Schedules L, M-1 and M-2.
Form 5471 & Form 5472
The two filings that most often go missing. Form 5471 for US persons with foreign corporations (including GILTI and Subpart F), and Form 5472 with pro forma 1120 for foreign-owned US LLCs — due even in a zero-activity year.
State, Multi-State & Back Filing
State income and franchise returns, nexus and apportionment for multi-state businesses, amended returns, delinquent-year catch-up and penalty abatement requests.
Find Your Filing Profile
Different forms, different rules, different risks. Here are the taxpayers we file for most often — one of these is probably you.
Individuals & Families
W-2 households, self-employed professionals and Schedule C sole proprietors, plus equity compensation, rental income and crypto activity. We file the base return and catch the credits and deductions software misses.
🛬 Nonresidents & Visa Holders
Form 1040-NR filers, dual-status arrival and departure years, treaty positions, and US rental or investment income earned from abroad.
🌐 Foreign-Owned US LLCs
Form 5472 plus pro forma 1120 — required every year, even with no revenue. Missing it costs $25,000.
💼 Partnerships & S-Corps
Multi-member LLCs, partnerships and S-corporations filing Forms 1065 and 1120-S. We issue clean K-1s on time, track owner basis year over year, and document reasonable compensation before the IRS asks about it.
🏢 Corporations & US Subsidiaries
C-corporations filing Form 1120, from funded startups to US subsidiaries of foreign parent companies. Book-to-tax reconciliation, transfer-pricing-aware related-party reporting, and the 5472 disclosures that come with foreign shareholders.
🤝 US Owners of Foreign Companies
Form 5471, GILTI and Subpart F, FBAR and Form 8938 — filed together, consistently, year after year.
Which Return Applies to You?
Three comparisons cover most of the confusion we hear on first calls: resident vs. nonresident, which entity return to file, and which international form is triggered. Use them for orientation — then let’s confirm your exact case on a free call.
Compare the choices side by side
Pick a comparison to see the full breakdown.
1040-NR
Form 1040 vs. Form 1040-NR
Your US tax residency decides the form — not your citizenship or visa label
| Form 1040 | Form 1040-NR | |
|---|---|---|
| Who files | Citizens, green card holders, and anyone meeting the Substantial Presence Test | Nonresident aliens with US-source income |
| Income taxed | Worldwide income | US-source income only |
| Deductions | Standard or itemized deductions available | No standard deduction (limited exceptions) |
| Filing status | Joint filing available for spouses | Generally single or married filing separately |
| Foreign reporting | FBAR, Form 8938, 5471 may all apply | Generally not required |
| Deadline | April 15 (Oct 15 extended) | April 15, or June 15 with no US wage withholding |
1120-S
1120
Form 1065 vs. 1120-S vs. 1120
Your entity type and election decide which business return is due — and when
| Form 1065 | Form 1120-S | Form 1120 | |
|---|---|---|---|
| Entity | Partnerships & multi-member LLCs | S-corporations | C-corporations |
| Who pays the tax | Partners, via K-1 | Shareholders, via K-1 | The corporation (21% federal) |
| Owner compensation | Guaranteed payments | W-2 reasonable salary required | W-2 salary; dividends taxed again |
| Foreign owners | Permitted | Nonresidents cannot be shareholders | Permitted — triggers Form 5472 |
| Deadline | March 15 (Sept 15 extended) | March 15 (Sept 15 extended) | April 15 (Oct 15 extended) |
5472
Form 5471 vs. Form 5472
Two directions of cross-border ownership — both with penalties that start in five figures
| Form 5471 | Form 5472 | |
|---|---|---|
| Direction | US person owns a foreign corporation | Foreign person owns a US entity |
| Who files | US officers, directors and shareholders, by category | US corporations and foreign-owned single-member LLCs |
| Filed with | Your Form 1040, 1065 or 1120 | Form 1120 — pro forma 1120 for disregarded LLCs |
| Reports | Ownership, financials, GILTI and Subpart F income | Reportable transactions with related parties |
| Zero activity? | Still required if a filing category applies | Still required — no revenue is not an exemption |
| Late penalty | From $10,000 per form, per year | $25,000 per year, per entity |
Still not sure which forms apply to you? Book a free 15-min call.
Book a Free Consultation25 Years of US Tax Law — Across Every Return Type
Manay CPA has prepared individual, business and cross-border returns since 1999. Our team files for W-2 households and single-owner LLCs as comfortably as it files for partnerships, S-corps, C-corps and US subsidiaries of foreign groups. Whatever your structure looks like, we have almost certainly filed it before.
- Licensed US CPAs, headquartered in Atlanta, Georgia
- Individual, business and international returns under one roof
- Federal and all 50 state jurisdictions, including multi-state apportionment
- IRS representation, notices and penalty abatement handled in-house
Your Data Stays Secure. Your Filings Stay On Time.
Documents move through a bank-grade encrypted client portal — you never email a K-1 or a passport scan. Every deadline that applies to you is tracked for you: March 15 for pass-throughs, April 15 for individuals and corporations, extension dates, quarterly estimates, and the international forms that ride along with them.
- Encrypted portal for all document exchange
- Automatic reminders for returns, extensions and estimated payments
- Multi-year filing history, basis and carryforwards maintained
- IRS Power of Attorney handling (Form 2848)
Recognition & Credentials
More than 25 years of trusted service, recognized by industry awards and professional credentials.

Best Woman Entrepreneur of the Year
Cobb Chamber · 2026
Top 25 Small Businesses of the Year
Cobb Chamber · 2026
Best of Georgia
Georgia Business Journal · 2025
One of America's Fastest-Growing Companies
Inc. 5000 · 2025Meet Our Tax Return Team
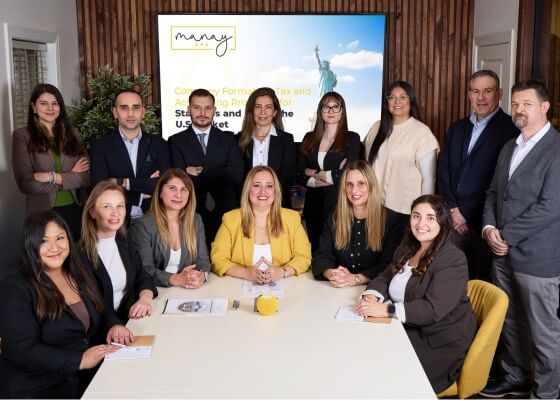
Real CPAs. Real Expertise. No Outsourcing.
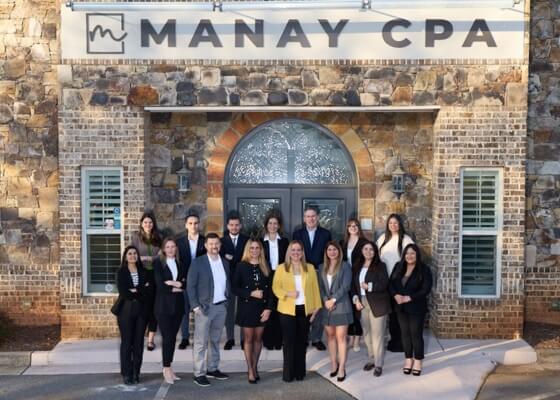
A Dedicated CPA on Every Return
Watch how we take a return from first call to e-file — for individuals, businesses and cross-border filers alike.
Click to watch the video
How a Filing Problem Usually Starts — and Ends
Most penalty letters begin with a form nobody mentioned. Scroll to follow the path we see most often.
Your Situation Changes
You start earning abroad, open an LLC, take on a partner, add a foreign shareholder, or move to the US mid-year. Your filing obligation changes with it.
“No Income, No Filing”
The most expensive assumption in US tax. A dormant LLC, an idle foreign company and a nonresident with US rental income all still have returns due.
The Penalty Letter Arrives
Form 5472 carries $25,000 per year. Form 5471 starts at $10,000. Late K-1s and unfiled state returns add their own layer on top.
You Work With Manay CPA
We scope every form you owe, file the current year, clean up prior years, request abatement where it applies — and keep the calendar from here on.
Your Situation Changes
New entity, new partner, new country — new forms.
“No Income, No Filing”
Zero activity does not remove a filing obligation.
The Penalty Letter Arrives
$25,000 for a missing 5472. $10,000 for a missing 5471.
You Work With Manay CPA
Current year filed, prior years cleaned up, calendar kept.
Let’s Confirm What You Actually Need to File.
Book a free 15-minute call with a US CPA. We’ll identify every return and information form that applies to you — and just as importantly, the ones that don’t.
- Free 15-min consultation — no commitment
- We map your federal, state and international forms on the call
- Transparent flat-fee pricing — no hourly billing surprises
- Licensed US CPAs — individual, business and cross-border returns
Get Your Free Tax Return Consultation
We respond within 1 business day.
Frequently Asked Questions
Which tax return form do I need to file?
Do I file Form 1040 or Form 1040-NR?
My US LLC is foreign-owned and had no activity. Do I still have to file?
What is Form 5471 and who has to file it?
What are the tax return filing deadlines?
Can one firm handle both my personal and business returns?
I haven’t filed for a few years. Can you help me catch up?
Do I need to file state returns as well?
How much does tax return preparation cost?
Do you handle foreign bank accounts and foreign asset reporting?
The Complete Guide to US Tax Returns
Individual, business and international returns explained — who files what, when it’s due, and where the expensive mistakes happen.
Start Here: Status and Entity Decide the Form
Almost every filing question resolves into two facts: what your US tax status is, and what kind of entity (if any) you own. An individual with no business files a Form 1040 or a Form 1040-NR. Add a business and a second return usually appears — Form 1065, Form 1120-S or Form 1120 — with a K-1 that feeds back into the individual return. Add foreign ownership in either direction and information returns such as Form 5471 or Form 5472 attach to that return. Getting these two facts right on day one prevents the majority of penalty situations we’re asked to clean up later.
Individual Returns — Form 1040 and Form 1040-NR
US citizens, green card holders and residents under the Substantial Presence Test report worldwide income on Form 1040, regardless of where they live or where the income arises. Nonresident aliens report only US-source income, on Form 1040-NR. The distinction matters far beyond which PDF gets filed: residents can use the standard deduction and joint filing, and are exposed to foreign reporting rules; nonresidents generally cannot use the standard deduction, are usually limited to single or married-filing-separately status, and face 30% flat withholding on certain fixed and determinable income unless a treaty reduces it.
Substantial Presence and Dual-Status Years
The Substantial Presence Test counts 31 days in the current year and 183 weighted days across three years. Cross that line and you become a US tax resident even on a temporary visa; stay below it and you remain a nonresident even if you spend months in the country. The year you arrive or depart is usually a dual-status year: nonresident for part of it, resident for the rest, with two sets of rules applied to one calendar year. First-year choice elections, closer-connection statements and treaty tie-breakers can all change the outcome, and each requires specific attachments to be filed correctly.
Schedule C, Rentals and Investment Income
Sole proprietors and single-member LLCs owned by individuals report business results on Schedule C of their 1040 and pay self-employment tax on net earnings. Rental owners report on Schedule E and must track depreciation carefully, since it will be recaptured on sale. Investors report capital gains on Schedule D and Form 8949 — including crypto disposals, which are now explicitly reported and matched against broker filings. Nonresidents with US rental property can elect to treat that income as effectively connected, taking deductions instead of flat gross withholding, but the election has to be made properly and consistently.
Business Returns — 1065, 1120-S and 1120
Partnerships and multi-member LLCs file Form 1065 and pass income to partners on Schedule K-1. S-corporations file Form 1120-S and do the same for shareholders, with the added requirement that owner-employees take reasonable W-2 compensation before distributions. C-corporations file Form 1120 and pay federal tax at the entity level, with dividends taxed again to shareholders. Choosing between them is not just a tax-rate exercise: eligibility, ownership restrictions, exit plans and investor expectations all bear on the decision.
Owner Compensation, Basis and K-1s
Three items generate most pass-through disputes. Reasonable compensation: too little S-corp salary invites reclassification and payroll penalties. Basis: distributions above basis become taxable, and losses are suspended when basis is exhausted — which means basis has to be tracked every year, not reconstructed years later. K-1 timing: partners and shareholders cannot finish their personal returns until the entity return is complete, so a late business filing cascades into late individual filings across every owner.
When Foreign Ownership Enters the Picture
Nonresidents cannot be S-corporation shareholders, so a foreign investor entering an S-corp terminates the election. Foreign persons can own C-corporations and partnerships, but foreign ownership triggers reporting: Form 5472 for the corporation, withholding obligations on partnership income allocable to foreign partners, and Form 1042-S reporting on certain payments. These are structural questions worth answering before the investment closes rather than at filing time.
International Information Returns
Information returns rarely create tax by themselves. They create penalties — assessed per form, per year, whether or not any tax was owed. They are the most common reason an otherwise compliant taxpayer receives a five-figure IRS notice, and the reason cross-border filings deserve a specialist rather than a seasonal preparer.
Form 5472 — Foreign-Owned US Entities
Form 5472 reports transactions between a US entity and its foreign related parties. It applies to US corporations with 25% foreign ownership and, critically, to foreign-owned single-member LLCs — which must file Form 5472 attached to a pro forma Form 1120 even when the LLC has no revenue, no employees and no activity beyond being formed. Capital contributions and payments made on the entity’s behalf are themselves reportable transactions. The penalty for failing to file is $25,000 per year, per entity, and it applies automatically.
Form 5471 — US Persons With Foreign Corporations
Form 5471 runs in the opposite direction: a US person who is an officer, director or shareholder of a foreign corporation reports that company to the IRS. Which of the filing categories applies determines which schedules are required, and controlled foreign corporation status can push GILTI or Subpart F income onto the owner’s personal return long before any dividend is paid. Elections under Section 962 and foreign tax credits can soften the result substantially, but only if claimed in the year they arise. The base late-filing penalty is $10,000 per form, per year, with escalation for continued failure.
FBAR, Form 8938 and Related Filings
FBAR (FinCEN Form 114) is required when the aggregate value of your foreign financial accounts exceeds $10,000 at any point in the calendar year, including accounts you merely have signature authority over. It’s filed with FinCEN, separately from your tax return, by April 15 with an automatic extension to October 15. Form 8938 covers a broader asset set under FATCA at higher, status-dependent thresholds and attaches to your return. Foreign mutual funds usually bring PFIC reporting on Form 8621, and interests in foreign partnerships bring Form 8865. Most cross-border clients file several of these together.
Deadlines at a Glance
These are the calendar-year dates we track for every client. An extension postpones filing, not payment — interest and late-payment penalties run from the original due date on any unpaid balance.
| Filing | Due date | Extended |
|---|---|---|
| Form 1065 & 1120-S (pass-throughs) | March 15 | September 15 |
| Form 1040 (individuals) | April 15 | October 15 |
| Form 1120 (C-corporations) | April 15 | October 15 |
| Form 1040-NR (nonresidents) | April 15 — June 15 with no US wage withholding | October 15 |
| Form 5471 / Form 5472 | With the return they attach to | Follows the return |
| FBAR (FinCEN 114) | April 15 | October 15 (automatic) |
Late, Missing or Incorrect Returns
Unfiled years are fixable, and they get more expensive the longer they wait. Delinquent income tax returns can be filed for prior years, with failure-to-file and failure-to-pay penalties often reduced through first-time abatement or a reasonable-cause request. Errors on filed returns are corrected by amendment — Form 1040-X for individuals, and amended or superseding returns for entities. Missing international information returns have dedicated procedures, including delinquent information return submission with a reasonable-cause statement. The one constant: relief options narrow sharply once the IRS opens contact, so voluntary correction is almost always the cheaper path.
Why a CPA Matters More Than Software
Consumer tax software handles a straightforward W-2 return well. It does not test your residency status, decide between an S-election and a C-corporation, track shareholder basis across years, prepare a Form 5471 schedule set, or notice that your dormant LLC owes a Form 5472. Those judgments require someone who has filed the form before and who will still be reachable when a notice arrives. At Manay CPA you get a licensed US CPA who prepares your individual and business returns together, files the international forms that come with them, keeps the multi-year continuity that basis and carryforwards depend on, and represents you before the IRS if questions come up.
Stop Guessing Which Form You Owe.
Join 8,000+ individuals and businesses who trust Manay CPA with their US returns.
Get Your Free Consultation